Watch Price Increases 2026: Rolex Up 7%, AP Raises 7.5%, Tudor 5.6% — Then Patek Cuts
By Zach Charles, Editor, Time on the Move
Published January 2, 2026 • Time on the Move
On January 1, 2026, Rolex, Audemars Piguet, and Tudor simultaneously raised their published retail price lists. Then, six weeks later, Patek Philippe moved the opposite direction — cutting US prices by 8% in what the brand described as a currency realignment. What it all means for buyers, collectors, and the secondary market.
The January 1 Price Increases
The first working day of 2026 brought updated price lists from three of the most-watched names in Swiss watchmaking. Rolex, Audemars Piguet, and Tudor each raised prices across their global markets simultaneously — a coordinated move that's become an annual ritual but one that still draws significant attention from buyers on waiting lists and collectors monitoring secondary market spreads.
| Brand | US Increase | UK Increase | Notable Example |
|---|---|---|---|
| Rolex | ~7% avg | ~5–6% | White-gold Daytona → $56,400 |
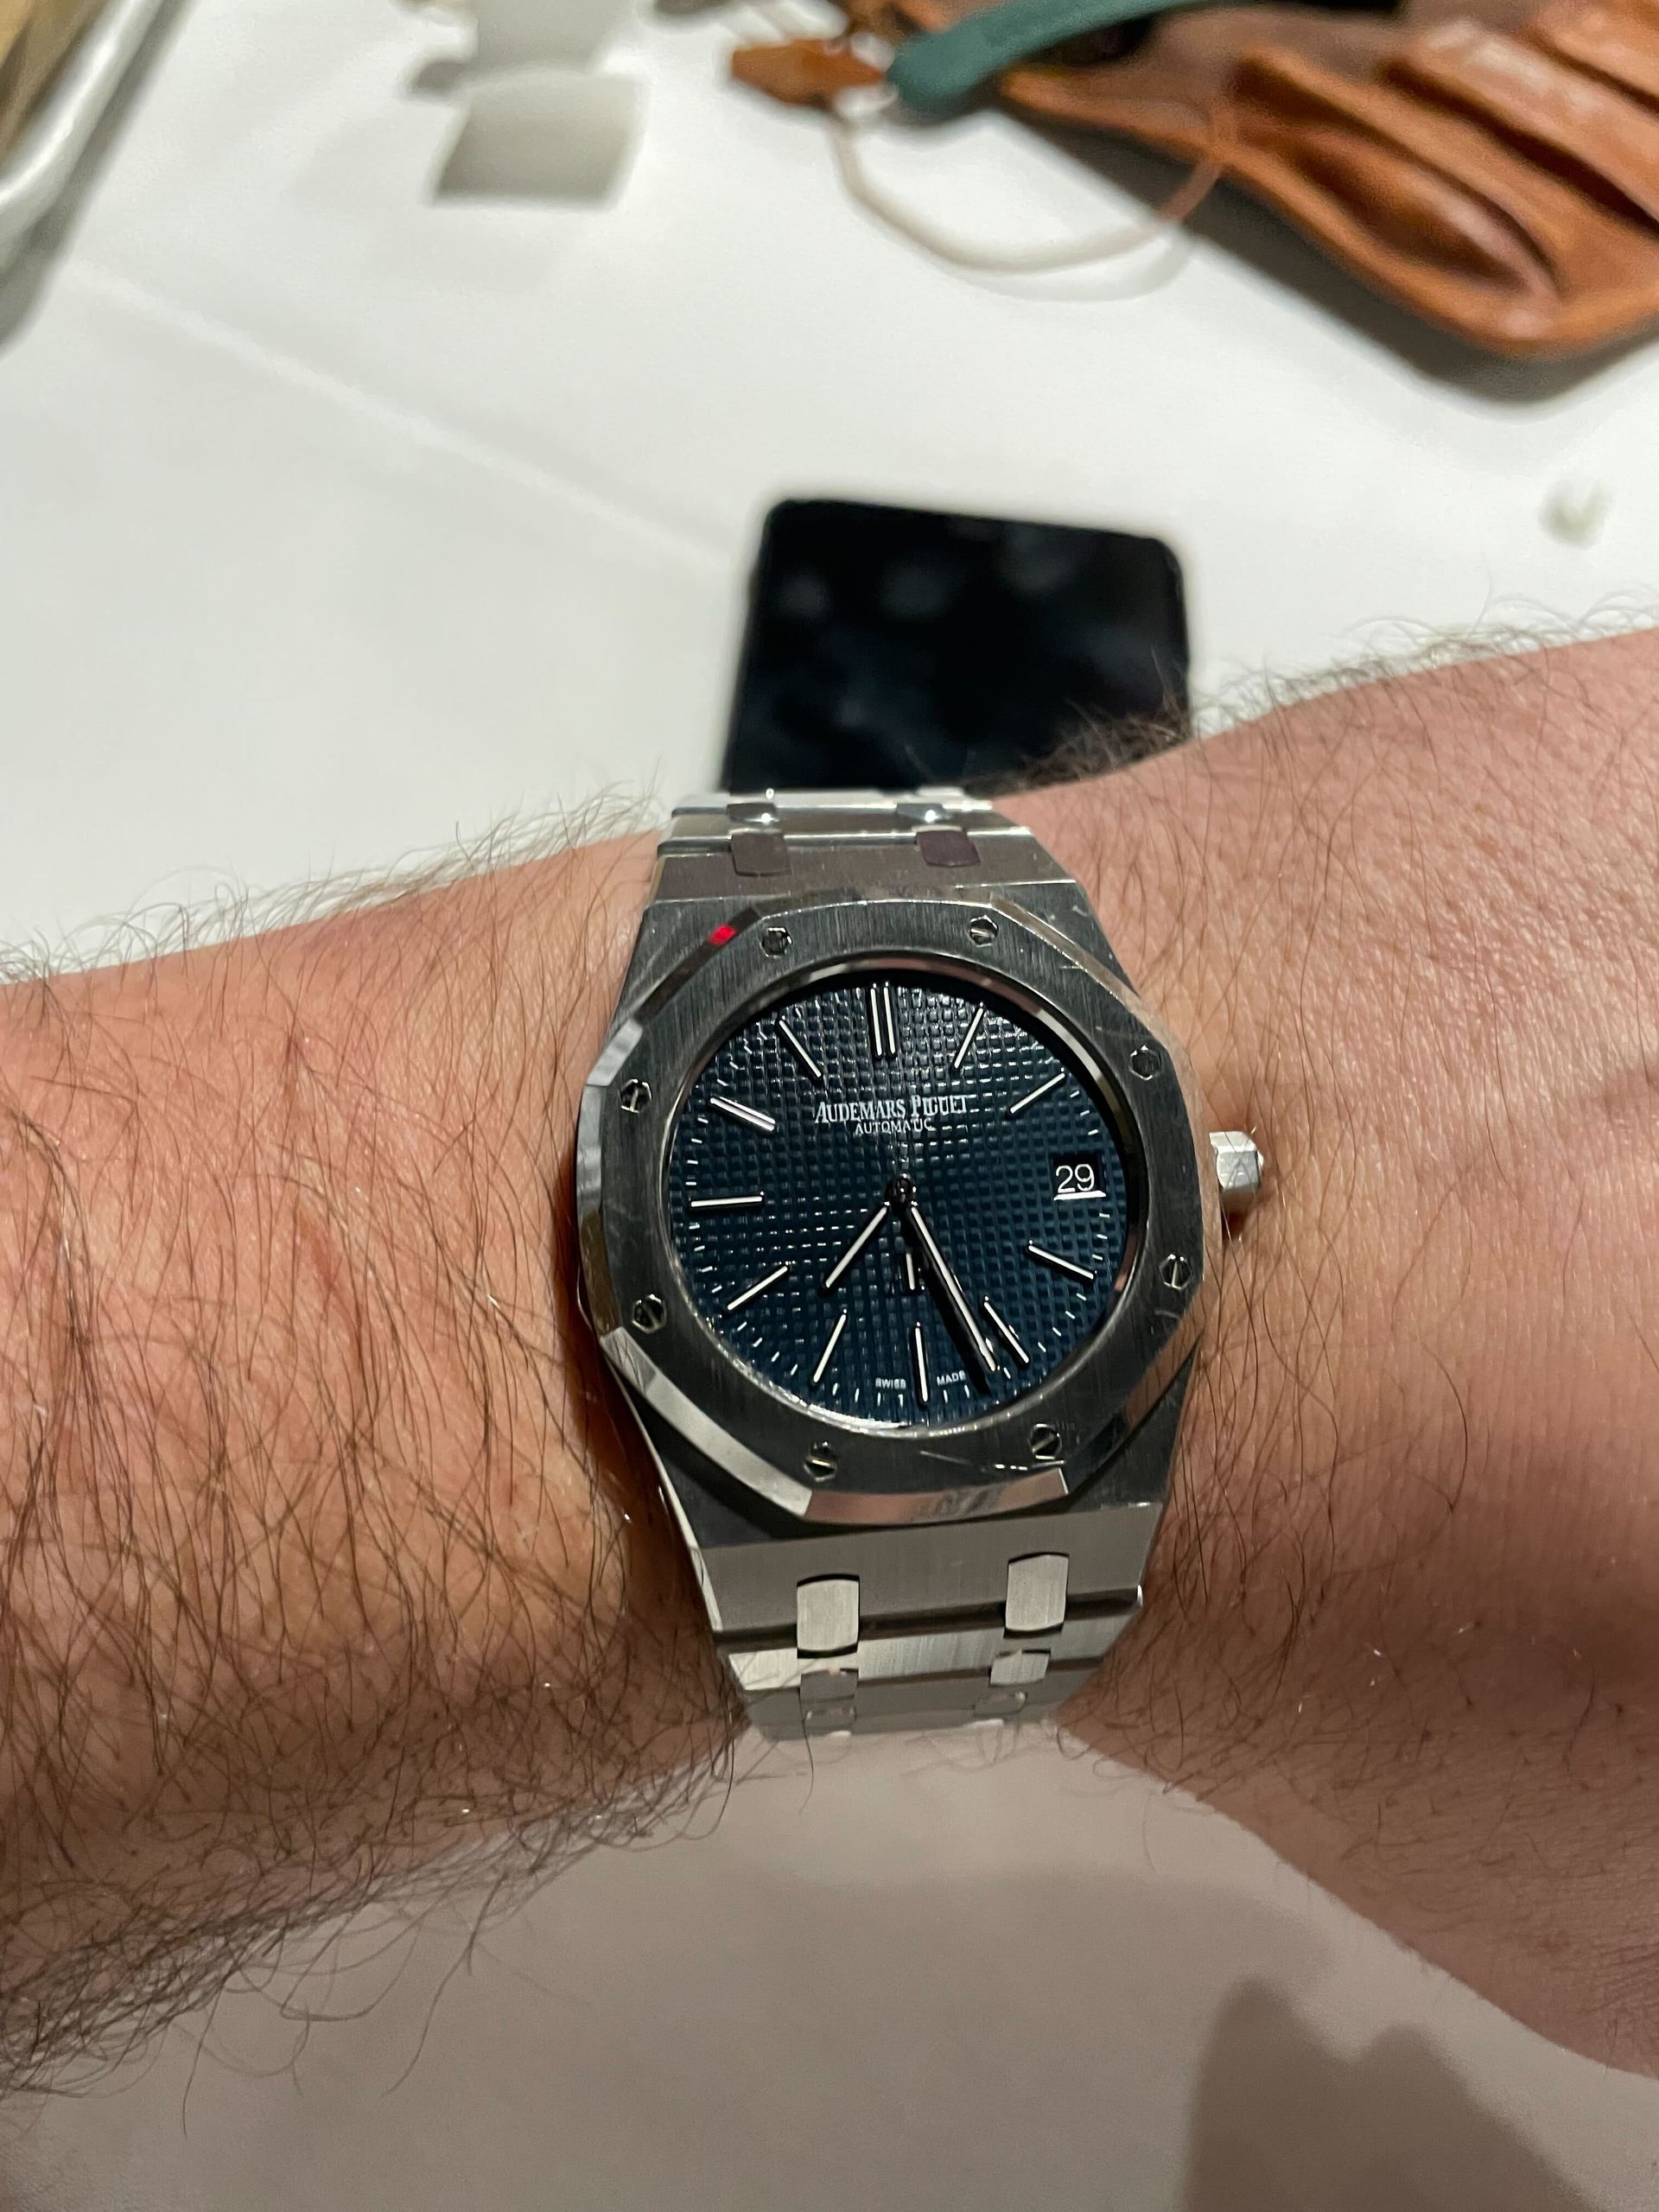
| Audemars Piguet | +7.5% | +2.5% | Steel Royal Oak Chrono: $40,500 → $44,400 |
| Tudor | +5.6% | +5.8% | Gold BB58: $36,500 → $39,400 |
| Patek Philippe | −8% (Feb) | — | FX realignment; still +14% vs end-2024 |
Rolex: The Details
Rolex applied a tiered approach. Stainless steel references — the Submariner Date, GMT-Master II, and entry-level Datejust — absorbed relatively modest increases in the 1–3% range. The heavier lifting came from gold and Rolesor references. The 40mm white-gold Daytona moved to $56,400, and the bi-metal and full-gold variants of the Datejust and Day-Date saw proportionally larger percentage increases, driven in part by the sustained rise in gold spot prices throughout 2025.
For buyers on authorised dealer waiting lists, the price change is largely academic — they're buying at whatever the retail price is when their allocation arrives. But for grey-market buyers tracking the spread between secondary and retail, even a 3% retail rise can shift the economics of a purchase meaningfully.
Audemars Piguet: The Biggest US Percentage Hike
AP's 7.5% US increase was the largest single-market percentage move among the three January 1 brands. The Royal Oak Chronograph in steel is the clearest example: at $40,500 in 2025, it was already a significant spend; at $44,400 in 2026, it's crossed the $44K threshold that puts it in direct competition with bespoke-specification alternatives.
The UK market saw a more modest 2.5% increase, which reflects currency dynamics — the pound's relative strength against the franc in late 2025 gave AP headroom to hold UK pricing more stable without sacrificing margin.
Tudor: Solid Across the Board
Tudor's 5.6% US increase is consistent with what the brand has implemented over recent years. The gold-on-gold Black Bay 58 — already a niche reference within an accessible brand — moved from $36,500 to $39,400, a $2,900 increase that underscores how quickly even Tudor's upper tier is moving toward the $40K mark.
For the steel Black Bay lineup — the brand's core volume — the increases were more moderate. The standard Black Bay 41 in steel moved by around 5%, keeping it competitive against similarly positioned alternatives from Omega, Breitling, and IWC.
Patek Philippe: The Counter-Move
The most unexpected pricing story of early 2026 came from Patek Philippe. On February 1, the brand cut its US retail prices by 8% — a move that generated significant coverage but requires careful contextualisation.
Patek had raised US prices by approximately 14% across 2025 in response to the franc's appreciation against the dollar. The February 2026 cut partially reversed that — but only partially. A buyer looking at a Nautilus today is still paying materially more than they would have at the end of 2024. The "cut" is better understood as a correction to an overshot adjustment than a genuine reduction in the cost of Patek ownership.
The secondary market reaction was muted. Nautilus and Aquanaut prices on platforms like Chrono24 barely moved — a signal that grey market pricing was already reflecting the realistic equilibrium independently of Patek's retail list movements.
What This Means for Buyers
For anyone on a waiting list for a steel Rolex or AP Royal Oak, the practical impact is limited — you pay whatever retail is when your watch arrives, and the price changes are a known annual variable. For secondary market buyers, the January increases narrow spreads on references that were already trading close to retail, making the grey market slightly less attractive on those pieces while having minimal effect on watches commanding significant premiums.